“Boot”与部分置换:商业房地产投资者套现(同时仍可递延纳税)指南

Boot and Partial Exchanges: How CRE Investors Can Cash Out and Still Defer Taxes with a 1031 Exchange.

As a savvy commercial real estate investor, you’ve likely watched the equity in your properties grow substantially. That’s the goal, after all. But this success presents a classic dilemma: your wealth is “trapped” in the asset, and accessing it traditionally means facing a significant capital gains tax bill.

Most investors are familiar with the Internal Revenue Code 第1031条交换, a powerful tool for deferring 100% of capital gains taxes by rolling all proceeds from a sale into a new, “like-kind” replacement property.

But what if you don’t want to roll 100%? What if you need liquidity? What if you want to pull some cash out to diversify, fund another project, or simply enjoy the fruits of your investment?

This is where a partial exchange comes in. It’s a sophisticated strategy that allows you to purposefully “cash out” a portion of your proceeds while still deferring the tax on the rest. The key to this strategy is understanding a single, critical concept: “开机”

What Exactly is "Boot" in a 1031 Exchange?

In the simplest terms, boot is any property or value received in an exchange that is 不是 “like-kind” property.

In a 1031 exchange, you are deferring taxes by swapping one investment property for another. The IRS reasons that since you haven’t technically “cashed out,” you shouldn’t have to pay tax. Boot is the part of the transaction where you did cash out, and it’s the part that becomes taxable.

Boot can take several forms:

  • 现金靴: This is the most straightforward. It’s any cash you receive from the sale proceeds that you do not reinvest in the new property. If you sell a property for $2 million and only buy a new one for $1.5 million, you will receive $500,000 in cash boot.
  • Mortgage Boot (Debt Relief): This is the one that trips up many investors. If the mortgage on the replacement property you are acquiring is less than the mortgage on the property you sold, the difference (the debt relief) is considered mortgage boot.
  • Personal Property Boot: This is less common in CRE but can include non-real-estate items that are part of the sale, like furniture, equipment, or business operations, if they aren’t replaced with similar items.

The golden rule is simple: You are taxed on the boot you receive. But here’s the good news: you are 仅 taxed on the boot, not the entire capital gain (as long as the rest of the transaction qualifies).

The Partial Exchange: Cashing Out Strategically

A “partial exchange” isn’t a failed 1031; it’s a planned 1031 where you intentionally receive boot. You are making a conscious decision to pay some tax now to gain a more valuable asset: liquidity.

How It Works: A Simple Example
Let’s break down the numbers to see this in action.
You sell Property A:

  • Sale Price: $3,000,000
  • Adjusted Basis (Original purchase price + improvements – depreciation): $1,500,000
  • Total Potential Capital Gain: $1,500,000

Scenario 1: No 1031 Exchange (The Tax Hit) If you simply sell the property and take the cash, you will pay capital gains tax (plus depreciation recapture) on the entire $1,500,000 gain.

Scenario 2: The Partial 1031 Exchange (The Strategy) You decide you want to pull $500,000 off the table.

  1. You sell Property A for $3,000,000. The funds go to your 合格中介(QI)。.
  2. You identify and purchase Property B, a replacement property, for $2,500,000.
  3. Your QI uses $2.5M of the proceeds to fund the new purchase and sends the remaining $500,000 in cash directly to you.

The Result:

  • Your Boot: You received $500,000 in cash boot.
  • Your Taxable Gain: You will pay capital gains tax only on that $500,000.
  • Your Deferred Gain: You have successfully deferred capital gains tax on the remaining $1,000,000 of your gain, which is now rolled into your new basis in Property B.

In this scenario, you get the immediate liquidity you need while protecting a full $1 million of your hard-earned gains from current taxation.

The Debt Trap: Don't Forget "Mortgage Boot"

The most critical mistake an investor can make in a partial exchange is forgetting about debt.
To fully defer all taxes in a standard 1031, you must follow two rules:

  1. Reinvest all cash proceeds.
  2. Acquire property with equal or greater debt.

If you violate the second rule, you create “mortgage boot.”
Example of the Debt Trap:

  • You sell Property A (Sale Price: $3M, Mortgage: $1M)
  • You buy Property B (Purchase Price: $3M, New Mortgage: $700,000)
  • You added $300,000 in new cash to make the deal work, so you reinvested all your cash proceeds.

你 still have a tax problem. Because your new mortgage ($700k) is $300,000 less than your old one ($1M), you have $300,000 in mortgage boot (debt relief), which is generally taxable.
In a partial exchange, your total taxable boot is the combination of cash boot and mortgage boot. Always analyze your debt structure before the sale.

Is a Partial Exchange Right for You?

A partial exchange is a powerful tool for balancing two competing needs: tax efficiency and access to capital. It may be the perfect strategy if:

  • You want to “right-size” your portfolio by trading down into a smaller or less management-intensive asset.
  • You need liquidity to fund a different investment, a business venture, or a capital improvement on another property.
  • You want to diversify your holdings by pulling some equity out of a single large asset.
  • You have personal financial needs and are willing to pay a manageable tax bill to access your cash.

A 1031 exchange, whether full or partial, is a complex financial maneuver. The rules are strict, the deadlines are absolute, and a simple mistake can have costly consequences.

This guide is for educational purposes, not tax advice. Before ever considering a sale, your first call should be to your CPA, tax attorney, and a reputable 合格中介(QI). They are your essential team to navigate the process, calculate your potential boot, and ensure your strategic “cash out” is executed flawlessly.

Would you like to explore how a partial 1031 exchange could help you access liquidity while deferring capital gains taxes?

作者

分享。

更多帖子

zh_CN简体中文
滚动到顶部
LIons Financial

阿里尔-塔沃尔

校长

Ariel Tavor 是 Lions Financial 的创始人兼首席常务董事。他对 Lions Financial 的规划是为客户提供保持最高专业价值的服务。他专注于企业对企业市场,因此能够在业务咨询、资本市场和风险管理等重点领域提供持续的咨询服务。Ariel 与首席执行官、资本投资基金和董事会合作,在高管薪酬、商业计划设计、兼并与收购、尽职调查和资产融资等方面为客户提供咨询服务。

阿里尔在金融服务行业拥有10年的从业经验。他曾在保险和投资公司任职,负责分析客户的财务状况,根据既定目标就资产配置提出建议,并维护长期客户关系。 凭借丰富的综合经验,阿里尔曾与来自卡车运输、酒店、商业地产、保险、制造业和科技等不同行业的公司首席执行官及其高管团队紧密合作。 他曾协助企业应对一系列具有挑战性的决策,包括:股权买卖协议、递延薪酬、员工团体福利、继任规划、并购、企业估值以及业务出售等。.

Ariel目前负责监督他们的家族办公室投资集团,并担任多家公司和房地产开发项目的董事会成员。他们的投资集团控制着多个行业的公司的投资组合。他们合作持有以下专业公司的股份--汽车分销--房地产资产管理--企业旅游--油墨邮寄制造,电子商务,金融服务,管理咨询,企业技术和食品概念。近年来,在个人承销的机会中,资金分配已经过渡到风险投资、私募股权和房地产投资的有限合伙投资。

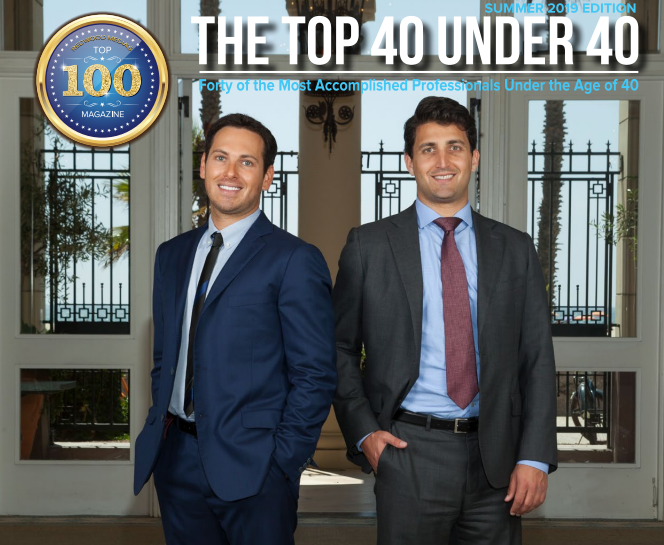
“40岁以下40强”

领导力表彰

Ariel Tavor是Lions Assurance Financial的创始人和主要总经理。他在Lions Assurance Financial的议程是为他的客户提供保持最高专业价值的服务。专注于企业对企业的市场,使得他在商业咨询、资本市场和风险管理等重点领域提供持续的咨询服务方面拥有熟练的专业知识。

金融界百大人物

业界认可

Lions Assurance Financial 是一家非常成功的独立商业咨询和财富管理顾问公司,专注于金融业的三个关键领域:商业咨询、资本市场和风险管理。Lions Assurance Financial 的团队经验丰富,专注于满足收入在 300 万至 5000 万之间的私营企业(包括独立企业主、家族企业和业务合作伙伴)的业务和财富管理需求。Lions Assurance Financial 与资本提供商合作,包括投资银行、私募股权公司、风险投资公司、资本咨询公司、认可投资者平台、商业银行和专业金融公司。

Exeleon

领导力与商业专题

在所有因素都相同的情况下,一个有活力的公司和一个不那么好的公司之间有什么根本区别?
答案很简单--迅速的行动。它是对情况形成想法的能力的结果,找到一个完美的反应。
然后采取相应行动。所有这一切,没有丝毫犹豫。众所周知,属于第二类的公司缺乏这种果断性,原因在于缺乏清晰的愿景,或者说缺乏处理上述步骤的能力。

硅评论

年度50家最具智慧的企业

有效的风险管理顾问会帮助个人和组织评估其风险,并制定应对损失的计划。风险管理是一个复杂的过程,没有一个放之四海而皆准的过程可供所有顾问使用。不过,顾问会使用某些常规方法来帮助您保护组织免受风险。风险管理顾问应该有能力识别贵企业面临的独特风险,并仔细评估各种情况。风险管理步骤中最关键的一步是发现并列出所有预期和意外风险。有各种咨询公司可以帮助您降低风险并照顾到企业的财务方面,但有一家公司在众多公司中脱颖而出,它就是 Lions Financial。该公司是一家位于纽约的独立金融服务和商业咨询公司。与狮子会金融公司常务董事 Ariel Tavor 的对话。Lions Assurance Financial 是一家非常成功的独立商业咨询和财富管理顾问公司,专注于金融业的三个关键领域:商业咨询、资本市场和风险管理。Lions Assurance Financial 的团队经验丰富,专注于满足收入在 300 万至 5000 万之间的私营企业(包括独立企业主、家族企业和业务合作伙伴)的业务和财富管理需求。Lions Assurance Financial 与资本提供商合作,包括投资银行、私募股权公司、风险投资公司、资本咨询公司、认可投资者平台、商业银行和专业金融公司。